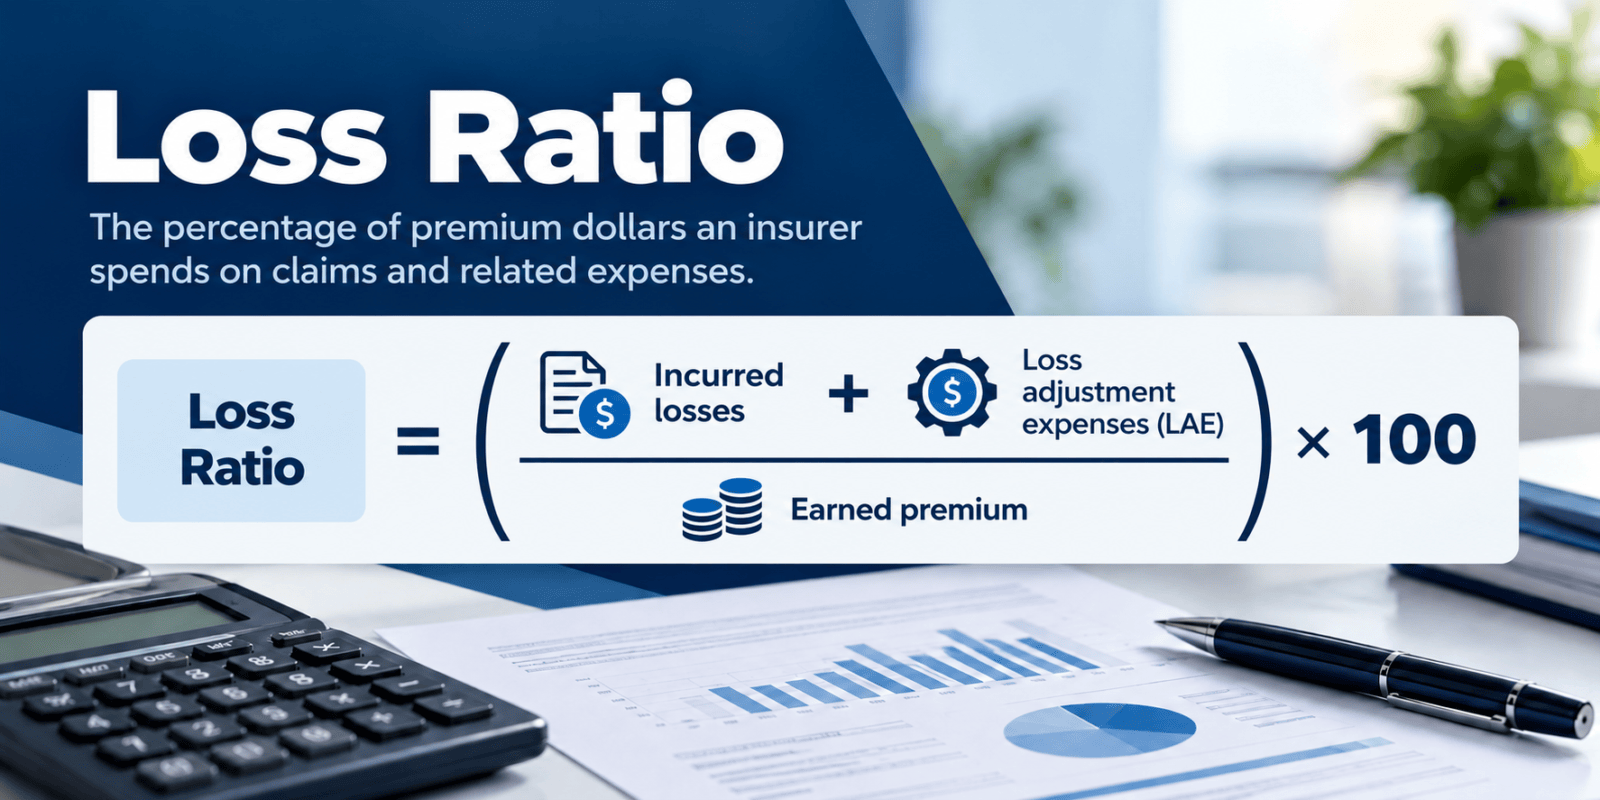
A loss ratio measures the percentage of an insurer’s earned premium that is used to cover claims and related loss adjustment expenses. It is one of the key measures insurers use to assess underwriting performance.
For example, a 65% loss ratio means that for every $100 of premium earned, the insurer incurred $65 in claims and claim-related expenses.
Loss Ratio Formula = (Incurred Losses + Loss Adjustment Expenses) ÷ Earned Premium × 100
What is Loss Ratio?
This measure represents the relationship between total premiums earned and actual losses incurred over a given period of time. It reveals how much an insurance company spent on paying claims and other expenses compared to the premium received.
It is a metric that specifically measures the profitability of insurance companies.
How Do You Calculate it?
Loss ratio = (((Incurred Losses + Loss Adjustment Expenses)/Premium earned) x 100
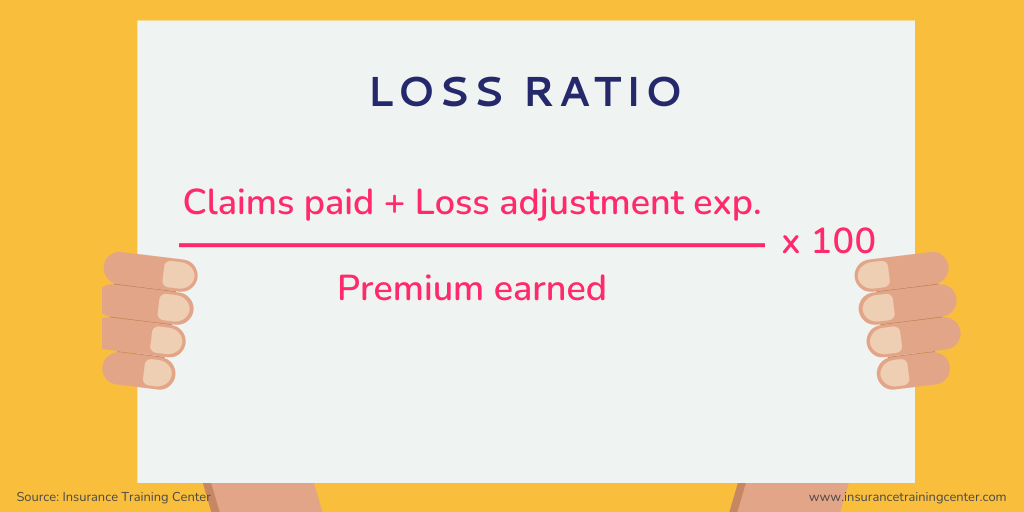
Loss Ratio Formula Breakdown:
Incurred Losses
Incurred losses represent the insurer’s cost of claims during a given period. They include claims that have already been paid as well as amounts reserved for claims that have occurred but have not yet been fully settled.
Adjustment Expenses
Loss adjustment expenses are the costs associated with investigating, managing and settling insurance claims. These may include expenses such as adjuster fees, legal costs and other claim-handling expenses.
Premium Earned
Earned premium is the portion of an insurance premium that an insurer has earned by providing coverage during a specific period. It differs from written premium because premium is earned over the period in which the insurer is actually providing coverage.
Loss Ratio vs. Combined Ratio: What’s the Difference?
These ratios measure different aspects of an insurer’s underwriting performance.
The loss ratio measures the proportion of earned premium used to cover incurred losses and loss adjustment expenses. For example, a 70% loss ratio means that for every $100 of premium earned, the insurer incurred $70 in losses and related claim expenses.
However, that does not mean the insurer made a $30 profit. The insurer still has other expenses associated with writing and administering the business, including commissions, acquisition costs, salaries and other operating expenses.
The combined ratio provides a broader measure of underwriting performance by taking both losses and underwriting expenses into account.
Combined Ratio = Loss Ratio + Expense Ratio
For example, if an insurer has a 70% loss ratio and a 25% expense ratio, its combined ratio is 95%. This means that for every $100 of premium earned, approximately $95 was consumed by losses and underwriting expenses.
A combined ratio below 100% generally indicates an underwriting profit, while a combined ratio above 100% generally indicates an underwriting loss. This is why the combined ratio provides a more complete picture of underwriting profitability than the loss ratio alone.
What Does the Loss Ratio Mean?
This ratio helps insurers understand how much of their earned premium is being used to cover incurred losses and loss adjustment expenses.
A lower ratio generally means that a smaller proportion of premium is being consumed by claims. However, a loss ratio should not be viewed as a direct measure of profitability. Insurers also have underwriting expenses such as commissions, acquisition costs, salaries and other operating expenses.
For this reason, there is no single loss ratio that can automatically be considered “good” or “bad.” An appropriate ratio depends on factors such as the type of insurance, the insurer’s expense structure, pricing strategy and historical loss experience.
Above 100%
A loss ratio above 100% means the insurer incurred more in losses and loss adjustment expenses than it earned in premium during the period being measured. For example, a 110% loss ratio means the insurer incurred $110 in losses and loss adjustment expenses for every $100 of premium earned. This indicates an underwriting concern, but it does not necessarily mean the insurance company as a whole is unprofitable.
Equal to 100%
A 100% loss ratio means that incurred losses and loss adjustment expenses equal earned premium. For every $100 of premium earned, $100 has been used to cover losses and related claim expenses. Because the insurer still has other underwriting expenses to pay, a 100% loss ratio would generally result in an underwriting loss.
Below 100%
A loss ratio below 100% means that losses and loss adjustment expenses are less than the premium earned. For example, a 70% loss ratio means that for every $100 of premium earned, $70 was used for losses and loss adjustment expenses, leaving $30 to cover the insurer’s other underwriting expenses and contribute toward underwriting profit. A lower loss ratio generally indicates better claims performance, but it does not necessarily mean greater profitability.
Sample calculations
Example 1. Loss Ratio for a Single Account
Suppose a homeowner pays $5,000 in earned premium over a period and the insurer incurs $6,000 in losses and loss adjustment expenses.
The calculation is:
$6,000 ÷ $5,000 × 100 = 120%
Interpretation
A 120% loss ratio means the insurer incurred $1.20 in losses and loss adjustment expenses for every $1.00 of premium earned from the account during that period. However, an underwriter would not necessarily make a decision based on one year’s loss ratio alone. The insurer would typically consider the account’s loss history over several years, including the frequency and severity of claims and whether the circumstances that caused the loss are likely to occur again.
For example, consider two homeowners who each generate $10,000 in earned premium over five years. One has five $1,000 claims, while the other has no claims for four years and then suffers a single $5,000 loss. Both have the same five-year loss ratio of 50%, but their loss histories tell very different stories.
The first homeowner has demonstrated a pattern of frequent claims, which may indicate an ongoing exposure. The second has experienced a single larger loss, which may or may not indicate an increased likelihood of future claims.
This is why insurers consider loss ratio alongside the frequency, severity and circumstances of losses over time.
Example 2. Loss Ratio for a Portfolio
Suppose an insurer earns $150,000 in premium from a portfolio during a given period. It incurs $60,000 in losses and $20,000 in loss adjustment expenses.
The calculation is:
($60,000 + $20,000) ÷ $150,000 × 100 = 53.3%
Interpretation
A 53.3% ratio means that approximately $53 of every $100 in earned premium was used to cover incurred losses and loss adjustment expenses.
The remaining approximately $47 per $100 of earned premium is available to cover commissions, acquisition costs and other underwriting expenses and potentially contribute to underwriting profit.
Whether a 53.3% loss ratio is considered favourable depends on the insurer’s expense structure, the type of insurance being written and its expected loss ratio.
How is Loss Ratio used?
By insurance companies
Insurance companies use it when making underwriting, pricing and management decisions.
For example, loss ratios may be used:
- when setting target premiums or determining whether rate changes may be necessary;
- to compare claims performance across different products, portfolios or lines of business;
- to identify trends in loss experience; and
- to assess performance against historical results or industry benchmarks.
This measure may also be incorporated into performance targets and incentive programs, particularly for employees responsible for underwriting or portfolio performance.
By regulators, investors, lenders, rating agencies, and consumer advocates
Regulators may monitor loss ratios as one of several indicators of an insurer’s financial condition and the performance of particular insurance products. In some jurisdictions and for certain products, minimum loss ratio requirements may also apply.
Investors, lenders and rating agencies may consider loss ratios when assessing an insurer’s underwriting performance and financial health. A rising loss ratio, for example, may indicate deteriorating claims experience or inadequate pricing, while an unusually low loss ratio may warrant further examination of pricing, claims experience or other factors.
Loss ratios should generally be considered alongside other financial and underwriting measures, including the expense ratio and combined ratio, rather than viewed in isolation.
What Is a Good Loss Ratio?
There is no single loss ratio that can be considered “good” across the insurance industry. An appropriate loss ratio depends on the type of insurance, the insurer’s expense structure, pricing strategy, historical loss experience and the characteristics of the portfolio being measured.
For example, a 60% loss ratio may be favourable for one line of business but too high for another. A lower loss ratio also does not automatically mean that an insurer is more profitable, since the loss ratio does not account for all of the expenses associated with underwriting and administering insurance policies.
Loss ratios are most meaningful when compared with relevant benchmarks, such as the insurer’s expected loss ratio, historical results, similar lines of business or comparable portfolios.
It is also important to consider loss ratios over time. A single large claim can significantly affect one year’s results, particularly for a small portfolio. Looking at several years of loss experience can provide a better indication of underlying claims performance and help distinguish an isolated severe loss from a recurring pattern of claims.
3 Ways to Improve the Loss Ratio
1. Improve claims management
Effective claims management can help control loss adjustment expenses and the ultimate cost of claims. Efficient investigation, early intervention, appropriate reserving and timely settlement can help prevent unnecessary costs from developing over the life of a claim.
Technology and automation can also make claims handling more efficient by reducing administrative work and helping claims professionals identify and respond to issues earlier.
2. Invest in underwriting excellence
Underwriting excellence is essential to maintaining strong loss performance and achieving sustainable growth.
Investing in underwriting excellence requires underwriters to develop strong technical knowledge and understand the factors that affect the risks they insure. This supports appropriate risk selection, coverage decisions and pricing that reflects the underlying exposure. Otherwise, insurers may incur losses as a result of inadequate pricing or poor risk selection.
Technology can also improve underwriting efficiency by reducing the amount of time underwriters spend on administrative tasks. According to Capgemini’s 2024 World Property and Casualty Insurance Report, commercial lines underwriters spend 41% of their time on administrative activities such as data entry, recordkeeping, information collection and internal administrative meetings. Only 33% of their time is spent on core underwriting activities such as risk assessment, premium calculation and book management. Capgemini
Automation and better access to data can free underwriters to spend more time assessing risks, making informed pricing decisions and managing their portfolios.
3. Invest in Loss Prevention and Risk Control
Insurers can improve loss experience by helping policyholders identify and reduce exposures before losses occur. Risk control measures may reduce the frequency or severity of claims, depending on the type of insurance.
Loss data can also help insurers identify recurring causes of claims and determine where risk management measures, changes in underwriting or coverage terms may help improve future results.
Frequently Asked Questions about Loss Ratio
What does a 60% loss ratio mean?
A 60% loss ratio means that an insurer incurred $60 in losses and loss adjustment expenses for every $100 of premium earned. The remaining $40 must still cover the insurer’s other underwriting expenses and potentially contribute to underwriting profit.
Is a lower always better?
A lower ratio is generally better, but it does not necessarily mean the insurer is more profitable. A loss ratio means that a smaller proportion of earned premium is being used to cover losses and loss adjustment expenses, but it does not by itself indicate overall profitability. Loss ratios should be evaluated in the context of the type of insurance, pricing, expenses and historical results.
What is the difference between loss ratio and combined ratio?
The loss ratio compares incurred losses and loss adjustment expenses with earned premium. The combined ratio also accounts for underwriting expenses and therefore provides a more complete measure of underwriting profitability.
Can a loss ratio be over 100%?
Yes. A loss ratio above 100% means the insurer incurred more in losses and loss adjustment expenses than it earned in premium during the period being measured.
Key Takeaways
- The loss ratio measures the percentage of earned premium used to cover incurred losses and loss adjustment expenses.
- A lower ratio generally indicates better loss performance because a smaller proportion of earned premium is being consumed by losses and related claim expenses.
- There is no single ratio that is considered “good” across the insurance industry. Appropriate loss ratios vary by insurer, line of business and portfolio.
- Loss performance should be evaluated over time. Both the frequency and severity of claims are important when assessing loss experience.
- A ratio below 100% does not necessarily mean an insurer is profitable. Other underwriting expenses, such as commissions, acquisition costs and operating expenses, must also be considered.
- The combined ratio provides a more complete measure of underwriting profitability by considering both losses and underwriting expenses.
- Effective claims management, strong underwriting and loss prevention can help insurers improve loss performance.
Learn more…